Every bubble debate usually ends up circling the wrong argument. With AI, most of the attention has gone to whether equity valuations are stretched, i.e. whether a price-to-earnings multiple of 25 or 30 on the technology complex is defensible. I think this is one of the less useful questions to ask. Valuations are largely a matter of opinion, while cash flows are something we can measure, and right now they point to probably the widest gap between capital deployed and revenue generated in modern economic history.
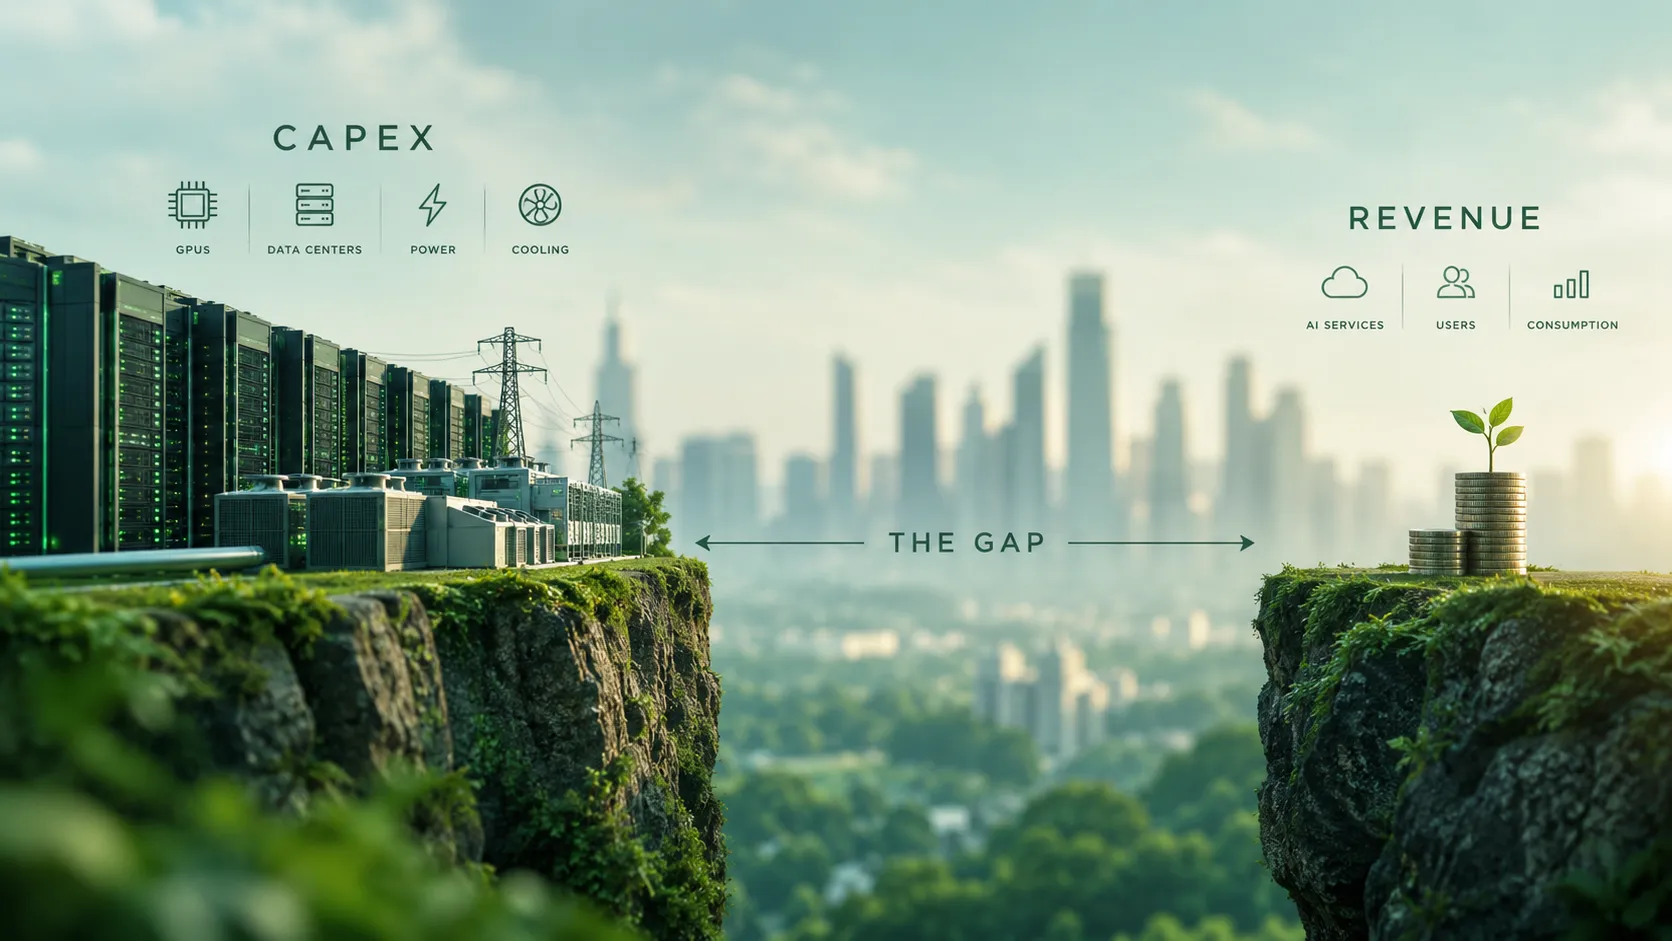
My view is simple: the AI boom is spending far more money than it is generating in revenue. How that gap is being financed, through circular deals, debt, and household investments, will determine whether a future correction is just a stock-market decline or becomes a broader credit crisis. The key question is: who is ultimately funding that gap, and what happens to them if AI spending slows down?
Capex has moved well ahead of any current revenue base
The raw numbers are a good place to start, because they now look less like corporate budgeting and more like national industrial policy.
The four largest US hyperscalers are collectively guiding to roughly $720bn-745 billion in capital expenditure for 2026, most of it going into AI data centers, GPUs, and power. Compared with about $410 billion in 2025, that’s a 77 percent year-over-year jump, and analysts are already projecting more than $1 trillion in 2027. Amazon alone has guided for around $200 billion in capex this year, more than double its 2025 outlay.
For context, this level of spending is larger than the annual GDP of most countries. It’s hard to find a revenue line inside these companies that justifies it on conventional payback math; the spending is mostly justified by a forecast, specifically the belief that agentic AI will turn infrastructure into recurring consumption. That might well prove correct. But it does mean the largest capital deployment cycle since the railway era is being underwritten by a projection rather than by demonstrated unit economics.
The required-revenue math keeps growing faster than actual AI sales
The most common framework for sizing the gap comes from a widely circulated venture analysis, and how its numbers have moved over time tells most of the story. It takes projected data center chip revenue, doubles it to cover the full cost of ownership (power, buildings, networking, cooling, etc.), then doubles it again to reflect the roughly 50 percent gross margin operators need for the spend to make sense. In late 2023, the annual AI revenue needed to justify the capex was $200 billion. By mid-2024, it was $600 billion. In 2026, with chip revenue running substantially higher and gigascale buildouts underway, the implied number is meaningfully larger, and the gap between that requirement and what the AI industry actually generates seems to have widened.
This is the part that is often overlooked: the target keeps moving. Every time companies increase their AI spending, future AI revenue has to grow even more to justify that spending. One estimate suggests there is already a roughly $600 billion annual gap between what major cloud companies spend on AI infrastructure and the revenue generated by the broader AI ecosystem. That gap could get even bigger in 2026 if spending continues to grow faster than revenue.
We’ve likely already passed the telecom benchmark
People who are skeptical about the AI boom often compare it to the telecom bubble; what surprised me is that the data suggests we’re already beyond it. AI spending is growing about 46% faster than AI-related revenue, a much greater divergence than during the 2001 telecom cycle, which came right before a long, painful correction in tech.
The usual rebuttal is that today’s spenders are profitable giants rather than leveraged startups laying fiber funded by junk bonds. I think that’s partly right, but it doesn’t address the main issue. The telecom comparison is less about who goes bankrupt and more about how overbuilding plays out. When capital formation is running 14 points further ahead of revenue than it did at the peak of the last big infrastructure cycle, some excess capacity is probably a given. The important question is who absorbs the losses when that capacity has to be written down. This matters even more for GPUs and other AI hardware, which can become outdated much faster than telecom infrastructure like fiber networks.
The other important point is that AI is clearly creating real value, but much of that value is going to users rather than the companies paying for the infrastructure.
For example, estimated US consumer benefits from generative AI reached about $172 billion a year in early 2026, up from $112 billion a year earlier. The typical user’s estimated benefit also tripled. At the same time, many AI tools remain free or very cheap. Generative AI has also reached 53% of the population within just three years, faster than the personal computer or the internet.
Put those two facts together, and the problem becomes clearer. Adoption is historically fast, the usefulness is measurably large, and very little of it is being monetized at the point of use. That’s great for households and much less great for payback periods. The dot-com era had a similar profile: e-commerce, search, email, etc. created enormous value, but the commercial returns often showed up years after many of the infrastructure investors who funded them had been wiped out. Being right about the technology but early on monetization has historically been a common way to lose money.
The way AI is financed could turn a market correction into a bigger financial problem
This is the part I’d expect policymakers to worry about more than any valuation metric. A lot of the funding gap is spread through channels that connect to the broader financial system, instead of just sitting on venture balance sheets that can fail quietly.
The IMF has flagged that circular investment and procurement arrangements among large AI players (where firms invest in each other while locking in future orders) create opacity and concentration risk, making ownership structures and valuations harder to assess. Growing reliance on debt financing, visible in high debt ratios and widening credit default spreads at some firms, adds to the concern. At the same time, a large share of household exposure now runs through benchmark indices, especially the S&P 500, largely via 401k retirement accounts (for the US market) and passive funds. That means a large and prolonged market decline could affect household wealth directly.
A simple example is a chip company investing in an AI company, which then agrees to buy computing capacity from a cloud provider that uses those same chips. The money effectively moves around the same group of companies. This can make revenue look stronger during the boom, but if spending slows, several companies can take losses at the same time. Add the large amount of household money invested in a relatively concentrated stock market, and the connection between an AI slowdown and household wealth may be stronger than it was during the dot-com crash. Back then, stock-market concentration was lower and retirement savings were less heavily invested in equities.
Conclusion
The AI bubble debate is usually about whether the technology is overvalued. I think the more important question is how the boom is being financed.
AI is creating real value very quickly, but companies are spending far more on infrastructure than they are currently generating in revenue. That gap is being supported by complex deals between AI companies, increasing debt, and household investments through retirement accounts and index funds.
None of this means a crash is guaranteed. But it does mean that if AI spending slows sharply, the impact may spread beyond technology stocks.
So for anyone tracking this in 2026, the most useful thing to watch is probably less about valuation multiples and more about whether the funding structure (debt levels, credit spreads, the circular deal flow, etc.) holds up through the years between now and real monetization.